

Quant finance MCP server for stock analysis, options analytics, implied volatility, Monte Carlo simulation, AI prediction, and backtesting.
- ✓Open-source license (MIT)
- ✓Actively maintained (<30d)
- ✓Clear description
- ✓Topics declared
- ✓Documented (README)
claude mcp add hpsilab-quant-finance-mcp -- python -m -U{
"mcpServers": {
"hpsilab-quant-finance-mcp": {
"command": "python",
"args": ["-m", "-U"]
}
}
}Resumen de MCP Servers
# HPSILab Quant Finance MCP Server for Stock & Options Analytics
<!-- mcp-name: io.github.haiyunsky/hpsilab-quant-finance-mcp -->
[](https://pypi.org/project/hpsilab-quant-finance-mcp/)
[](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/actions/workflows/ci.yml)
[](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/LICENSE)
HPSILab is an open-source Python quantitative finance MCP server for research on
US equities, ETFs, and supported options. It brings stock signals, implied
volatility, options analytics, Monte Carlo simulation, AI prediction,
backtesting, and risk analysis into ChatGPT, Claude, Cursor, VS Code, and other
MCP clients. Connect once, ask in natural language, and receive structured
results that an assistant can compare and explain.
> Research and educational use only. HPSILab does not provide investment advice
> and does not execute trades.
[Get a Free API Key](https://hpsilab.com/register) · [Pricing](https://hpsilab.com/pricing) · [Tool reference](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/tools.md) · [Client setup](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/client-setup.md) · [Python SDK](https://pypi.org/project/hpsilab-mcp/)
| | |
| --- | --- |
| **Registry name** | `io.github.haiyunsky/hpsilab-quant-finance-mcp` |
| **Version** | 0.10.0 — a source checkout reports `0.10.0+source` |
| **Transports** | Streamable HTTP (hosted) · stdio (PyPI package) |
| **Remote endpoint** | `https://hpsilab.com/mcp` |
| **Package** | `pip install -U hpsilab-quant-finance-mcp` |
| **Authentication** | Bearer API key, or `HPSILAB_API_KEY` for stdio |
| **Tools** | 10 — nine financial research tools plus `register_account` |
## Connect: hosted Streamable HTTP
Recommended, and requires no local installation.
1. [Register a free account](https://hpsilab.com/register), sign in, and
generate an API key from Settings.
2. Add the server to your client's **private** configuration, replacing
`hpsi_your_key`. Never commit a real key or paste one into chat.
The example below is Claude Code's `.mcp.json`; other clients use different
configuration schemas, all covered in
[client setup](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/client-setup.md).
```json
{
"mcpServers": {
"hpsilab": {
"type": "http",
"url": "https://hpsilab.com/mcp",
"headers": {
"Authorization": "Bearer hpsi_your_key"
}
}
}
}
```
3. Verify the connection:
```text
Use HPSILab to analyze AAPL. Separate observed metrics from interpretation,
identify conflicting signals, and finish with a concise risk summary.
```
All financial research tools require a valid API key. See
[authentication](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/authentication.md)
for key handling and rotation.
## Connect: local stdio
For clients that require a local process:
```bash
pip install -U hpsilab-quant-finance-mcp
```
This example uses the `mcpServers` schema supported by Claude and Cursor; VS
Code and GitHub Copilot use a `servers` schema instead.
```json
{
"mcpServers": {
"hpsilab": {
"command": "hpsilab-quant-finance-mcp",
"env": {
"HPSILAB_API_KEY": "hpsi_your_key"
}
}
}
}
```
Then verify it through the MCP client:
```text
Use HPSILab to get the AI prediction for NVDA and summarize the model consensus.
```
The client discovers tools with MCP `tools/list` and invokes them with
`tools/call`. See
[local setup](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/self-hosting.md)
and
[Python usage](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/python-sdk.md),
which also covers calling the tool functions directly from Python.
## Tools
Nine financial research tools, plus `register_account`. Tool names and parameter
meanings are part of the public compatibility contract.
| Tool | What it returns | Behavior |
| --- | --- | --- |
| `analyze_stock` | Aggregate directional and quantitative stock analysis | Read-only |
| `get_ai_prediction` | Next-session prediction, confidence, and model consensus | Read-only |
| `get_iv_radar` | IV level, rank, percentile, skew, and regime | Read-only |
| `get_option_pressure` | Max pain, gamma walls, expected move, and pressure zones | Read-only |
| `get_monte_carlo` | 10-trading-day simulated distribution and probabilities | Read-only |
| `get_equity_curve` | Strategy backtests and risk-adjusted performance | Read-only |
| `get_pretrade_risk_scan` | Position, exposure, correlation, and risk checks | Read-only |
| `generate_stock_images` | Hosted stock and options chart artifacts | Creates an artifact; not idempotent |
| `generate_stock_research_report` | Structured Markdown research report and timestamp | Creates an artifact; not idempotent |
| `register_account` | Account credentials for the authenticated caller | Creates an account and sends email; not idempotent |
Research tools accept one exchange ticker such as `NVDA`, `SPY`, or `BRK.B`;
company names are not accepted. Live results can change between calls. Artifact
tools can consume quota and should not be retried automatically.
Full inputs, outputs, side effects, and tool-selection guidance are in
[docs/tools.md](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/tools.md).
### Monte Carlo research example
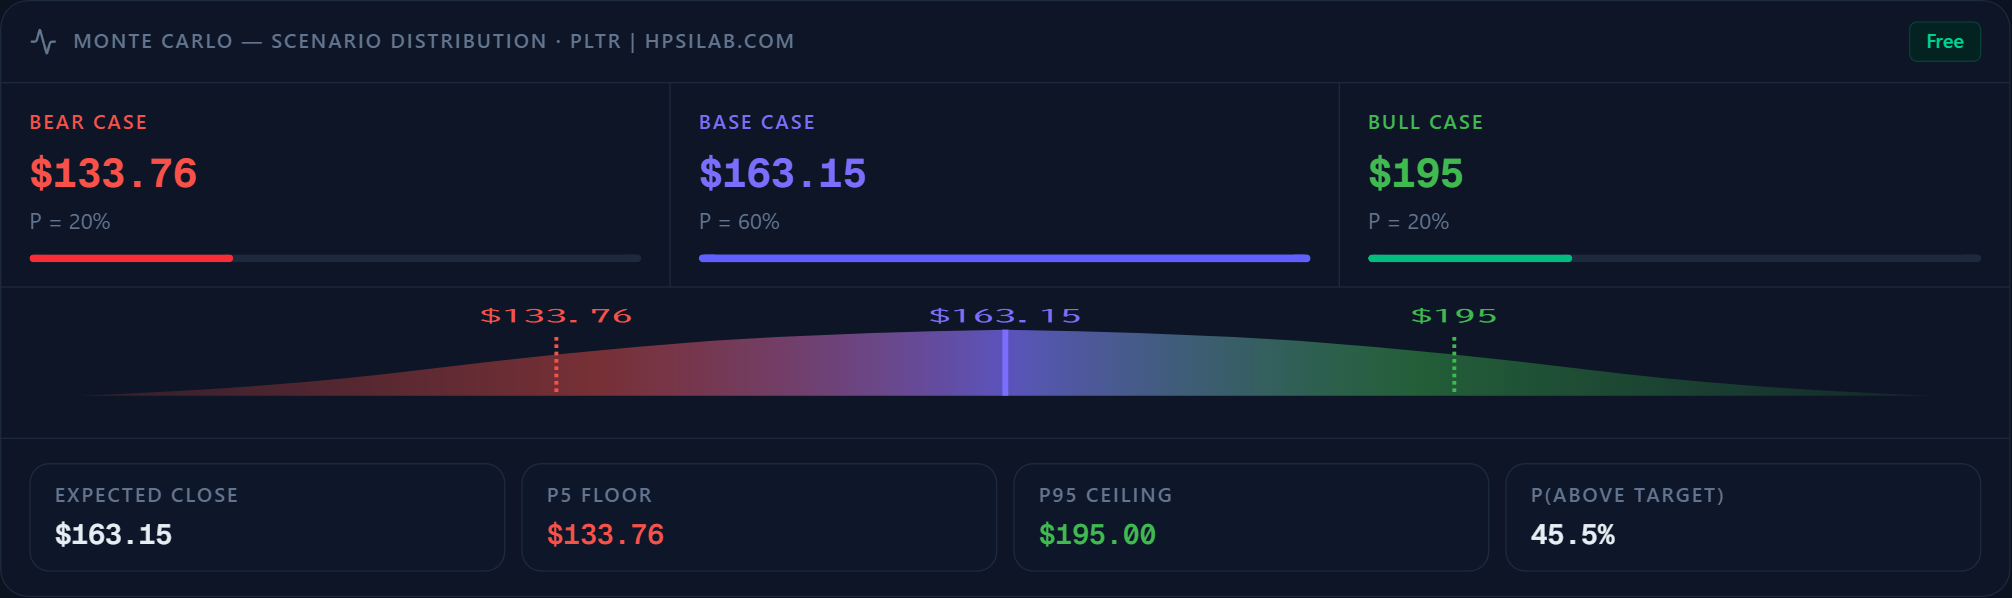
Example visualization of scenario-based Monte Carlo research output. Results
depend on the selected inputs and model assumptions. See
[`get_monte_carlo`](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/tools.md#financial-research-tools)
for tool details.
## Copy-ready prompts
### Claude
```text
Use HPSILab to analyze NVDA. Summarize the directional signal, AI model
consensus, IV regime, options pressure, 10-day Monte Carlo range, and the
three most important risks. Distinguish tool data from interpretation.
```
### Cursor
```text
Use HPSILab's IV radar and option-pressure tools for SPY. Compare IV rank,
percentile, skew, expected move, max pain, gamma wall, and pressure zones.
Return a compact table and do not recommend a trade.
```
### ChatGPT
```text
Run the HPSILab pre-trade risk scan for TSLA. Explain every warning or failed
check, preserve unavailable fields as unavailable, and quote the returned
reason instead of guessing. Do not execute or recommend a trade.
```
Setup guidance covers ChatGPT, Claude, Cursor, VS Code, GitHub Copilot,
Continue, and Kimi. See the
[client setup guide](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/client-setup.md)
for each client's transport and configuration format.
## Errors, retries, and limits
Every failure is a structured object with a stable `error_code`, never prose an
agent has to pattern-match. Five refusals matter, because each has a different
remedy:
| `error_code` | Meaning | What resolves it |
| --- | --- | --- |
| `api_key_required` | No key is configured | Registering. Nothing is sent downstream |
| `rate_limited` | Calling too fast (429) | Waiting — `next_actions` carries the seconds |
| `insufficient_credits` | The Credit balance is empty (402) | Adding Credits, or registering for trial Credits |
| `allowance_exhausted` | The free evaluation ceiling is spent (402) | Registering, or verifying an email. Money does not lift it |
| `settlement_unknown` | A payment whose outcome is unconfirmed | Reconciliation. **Do not retry it and do not pay again** |
Without a key the package stops locally, before constructing the downstream
client or sending a request:
```json
{
"error": "api_key_required",
"message": "A free API key is required.",
"register_url": "https://hpsilab.com/register",
"docs_url": "https://hpsilab.com/developer/v2"
}
```
401 and 402 responses are never retried. A 429 is retried only when it carries a
valid `Retry-After`. Read-only calls use a finite retry budget for timeouts and
recoverable 500/502/503/504 responses; artifact-producing calls are not retried
automatically. The package also applies one process-local safeguard of 10
requests per rolling minute per API key — burst protection, not a quota, since
only the hosted service knows the balance and the plan.
Field-by-field payloads, the Credits circuit breaker, and the reasoning behind
each remedy are in
[docs/authentication.md](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/authentication.md)
and
[docs/python-sdk.md](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/docs/python-sdk.md).
## Why HPSILab
HPSILab gives assistants typed inputs, structured outputs, ticker validation,
machine-readable errors, and dedicated tools instead of invented metrics. It
supports US-listed equities, ETFs, and supported options data; coverage and
limits depend on the hosted service and plan.
## Safety and license
HPSILab is for research and education only. Outputs may be incomplete, delayed,
or wrong and are not investment, financial, or trading advice. The MCP server has
no brokerage connectivity, order entry, or trade-execution capability.
Licensed under the
[MIT License](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/LICENSE).
Contributions are welcome; read
[AGENTS.md](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/AGENTS.md)
and
[CONTRIBUTING.md](https://github.com/haiyunsky/hpsilab-quant-finance-mcp/blob/main/CONTRIBUTING.md)
before proposing public schema changes.
Lo que la gente pregunta sobre hpsilab-quant-finance-mcp
¿Qué es haiyunsky/hpsilab-quant-finance-mcp?
+
haiyunsky/hpsilab-quant-finance-mcp es mcp servers para el ecosistema de Claude AI. Quant finance MCP server for stock analysis, options analytics, implied volatility, Monte Carlo simulation, AI prediction, and backtesting. Tiene 1 estrellas en GitHub y su última actualización registrada es del 2026-09-30.
¿Cómo se instala hpsilab-quant-finance-mcp?
+
Puedes instalar hpsilab-quant-finance-mcp clonando el repositorio (https://github.com/haiyunsky/hpsilab-quant-finance-mcp) o siguiendo las instrucciones del README en GitHub. ClaudeWave también te ofrece bloques de instalación rápida en esta misma página.
¿Es seguro usar haiyunsky/hpsilab-quant-finance-mcp?
+
Nuestro agente de seguridad ha analizado haiyunsky/hpsilab-quant-finance-mcp y le ha asignado un Trust Score de 95/100 (tier: Verified). Revisa el desglose completo de comprobaciones superadas y flags en esta página.
¿Quién mantiene haiyunsky/hpsilab-quant-finance-mcp?
+
haiyunsky/hpsilab-quant-finance-mcp es mantenido por haiyunsky. La última actividad registrada en GitHub es del 2026-09-30, con 0 issues abiertos.
¿Hay alternativas a hpsilab-quant-finance-mcp?
+
Sí. En ClaudeWave puedes explorar mcp servers similares en /categories/mcp, ordenados por popularidad o actividad reciente.
Despliega hpsilab-quant-finance-mcp en tu cloud
Lleva este repo a producción en minutos. Cada plataforma genera su propio entorno con variables de entorno editables.
¿Mantienes este repo? Añade un badge a tu README
Pega el badge en tu README de GitHub para mostrar que está auditado por ClaudeWave. Cada badge enlaza de vuelta a esta página y muestra el Trust Score actual.
[](https://claudewave.com/repo/haiyunsky-hpsilab-quant-finance-mcp)<a href="https://claudewave.com/repo/haiyunsky-hpsilab-quant-finance-mcp"><img src="https://claudewave.com/api/badge/haiyunsky-hpsilab-quant-finance-mcp" alt="Featured on ClaudeWave: haiyunsky/hpsilab-quant-finance-mcp" width="320" height="64" /></a>Más MCP Servers

Fair-code workflow automation platform with native AI capabilities. Combine visual building with custom code, self-host or cloud, 400+ integrations.

User-friendly AI Interface (Supports Ollama, OpenAI API, ...)

An open-source AI agent that brings the power of Gemini directly into your terminal.

Real-time global intelligence dashboard. AI-powered news aggregation, geopolitical monitoring, and infrastructure tracking in a unified situational awareness interface

🕷️ An adaptive Web Scraping framework that handles everything from a single request to a full-scale crawl! Don't be shy, join here: https://discord.gg/EMgGbDceNQ and follow here for daily tips and tricks: https://x.com/Scrapling_dev

The fastest path to AI-powered full stack observability, even for lean teams.